Types of Financial Advisors in India and How They Get Paid
When people need help with their money, they often approach someone they call a “financial advisor.” But in India, the term financial advisor is used very broadly.
An insurance advisor, a bank relationship manager, a mutual fund distributor and a SEBI Registered Investment Adviser may all help people with financial matters. However, their qualifications, responsibilities and compensation models can be very different.
Understanding these differences is important because the person advising you may be paid:
- By an insurance company
- By a bank
- By a mutual fund company
- Directly by you
- Or through a combination of salary, incentives or other permitted compensation
The way a financial professional is paid does not automatically determine whether the advice is good or bad. However, it can help you understand possible conflicts of interest.
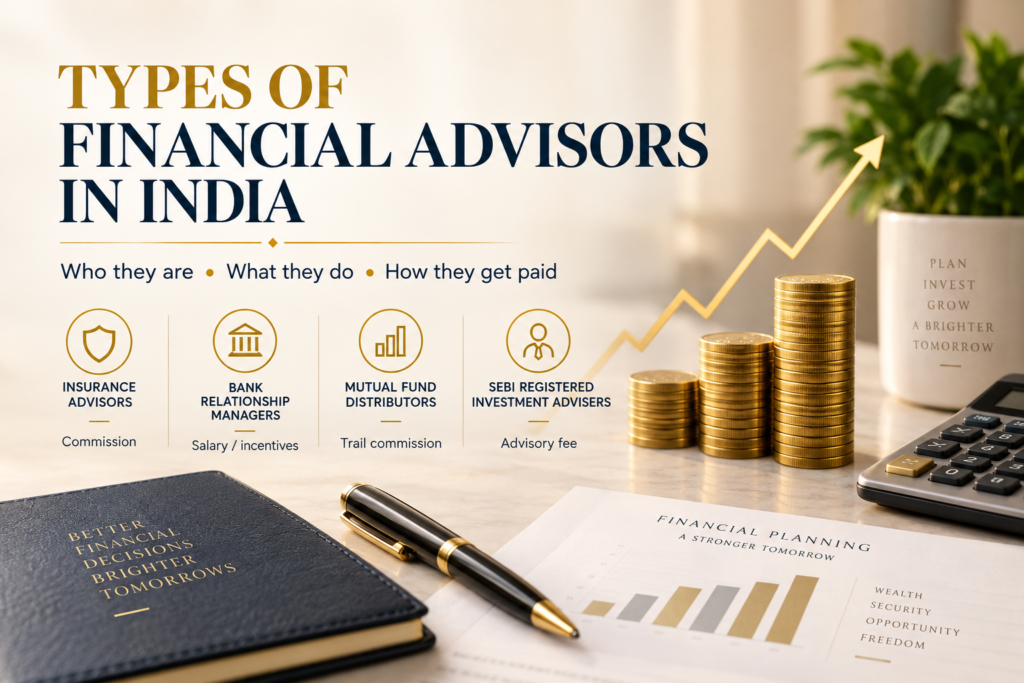
Before choosing anyone to guide you financially, three questions are worth asking:
- Who are they?
- What do they do?
- How are they paid?
Let us understand the common types of financial professionals in India.
1. Insurance Advisors
Who are they?
Insurance advisors are professionals who help individuals and families understand and purchase insurance products.
Some insurance advisors work with only one insurance company, while others may be associated with intermediaries that offer products from multiple insurers.
What do they do?
An insurance advisor may help you:
- To understand your insurance needs
- Explain insurance policies
- Help with policy purchase
- Provide policy servicing
- Assist during claims
How are they paid?
Most insurance advisors do not charge the customer a separate advisory fee. Instead, they generally receive commission or other permitted compensation through the insurance distribution system.
This does not mean that every commission-based recommendation is unsuitable.
However, customers should ask:
1. Why is this policy suitable for me?
2.How much insurance do I actually need?
3.What are the exclusions and limitations?
A good insurance advisor should be able to answer these questions clearly.
2. Bank Relationship Managers
Who are they?
Bank Relationship Managers, commonly called RMs, are employees or representatives of banks who manage customer relationships.
Their primary responsibility is usually to manage the customer’s relationship with the bank.
What do they do?
A bank relationship manager may assist with a wide range of financial products and services.The RM may therefore be expected to
- Manage customer relationships
- Retain customers
- Increase product usage
- Meet business targets
- Introduce products offered or distributed by the bank
The products suggested may therefore come from the bank’s own product range or from companies with which the bank has distribution arrangements. This is different from independently analysing every product available in the market.
A recommendation made by a bank employee may still be suitable and useful.
However, the customer should understand whether the person is:
- Giving regulated personalised investment advice
- Distributing a product
- Introducing a banking product
- Or facilitating a transaction
These roles are not always the same.
How are they paid?
Bank relationship managers are generally paid a salary by the bank.
Depending on the bank and the employee’s role, their compensation may also include:
- Performance incentives
- Bonuses
- Business-linked rewards
- Sales-linked incentives
The customer normally does not pay the RM directly.
However, the bank may earn income from the products and services purchased by the customer.
3. Mutual Fund Distributors
Who are they?
Mutual Fund Distributors, commonly called MFDs, help investors invest in mutual fund schemes.They generally operate with the required registration and identification applicable to mutual fund distribution.
Their main area of work is helping investors access mutual fund products.They generally facilitate investments in Regular Plans of mutual fund schemes.
What do they do?
A mutual fund distributor provide many useful services.
1.Help investors select mutual funds
2.Help with transactions
3.Provide account servicing
4.Provide portfolio support
However, the regulatory and professional capacity in which such support is provided should be clearly understood.
How are they paid?
Mutual fund distributors are generally paid by the Asset Management Company through trail commission on investments made through Regular Plans.
The investor usually does not receive a separate bill for this commission.
Instead, distribution costs are reflected through the expense structure of the Regular Plan.
4. SEBI Registered Investment Advisers
Who are they?
A SEBI Registered Investment Adviser, commonly called an RIA, is an individual or entity registered to provide investment advisory services under the applicable SEBI framework.
The role of an Investment Adviser is different from simply selling a financial product. An RIA is expected to provide advice based on the client’s individual circumstances.
The purpose is to provide personalised advice rather than simply distribute a product.
What do they do?
The exact scope may differ between advisers, but a SEBI Registered Investment Adviser may provide services such as:
1.Risk profiling
2.Suitability assessment
3.Goal-based investment planning
4.Asset allocation
5.Investment recommendations
6.Portfolio reviews
How are they paid?
A SEBI Registered Investment Adviser is paid an advisory fee by the client. This is the biggest difference between an advisory model and many commission-based distribution models.
The adviser may charge through a permitted fee structure, subject to applicable SEBI regulations.
Depending on the model, this may include:
- A fixed fee
- A fee linked to Assets Under Advice
The exact fee varies from adviser to adviser.
Which Type of Financial Advisor Should You Choose?
The term “financial advisor” can mean very different things in India.
An insurance advisor primarily helps with insurance. A bank relationship manager represents the bank and provides access to banking and financial products. A mutual fund distributor helps investors access and service mutual fund investments and generally earns trail commission from Regular Plans. A SEBI Registered Investment Adviser provides personalized investment advice and charges the client an advisory fee.
The objective is not to label one model as good and another as bad.
The real objective is transparency.
Before accepting any financial recommendation, understand:
1.Who is advising you?
2.What exactly are they doing for you?
3.How are they getting paid?
When these three answers are clear, you are in a much better position to evaluate financial advice and make informed decisions.